

The three-year lease on my Lexus RZ EV ends in a few months. After looking at an EV replacement, test-driving several cars, checking reviews, and doing plenty of research, I decided to just purchase my 2023 model. While I found a number of attractive EV options—mainly from Toyota and Hyundai—none matched the combination of price and luxury I’ve been enjoying. Considering my car has only 15,000 miles, it’s nearly as good as new. Another factor was the buyout price was below current retail value due to the recent surge in used EV demand. Six months back it was just the opposite.
I contacted my Lexus dealer about the buyout and they claimed they could get me some of the best financing rates, but insisted I visit in person so they could inspect the car and discuss an extended warranty.
“There’s no need to see my car, I explained. ” I still have a year of warranty remaining. Just tell me the range of interest rates you’ve been able to offer and any fees you charge. If you’re competitive, I’ll be happy to come in,” I said. They refused, saying that’s not how they work. I countered with, “Well, that’s not how I work.”
So, I decided to shop for an auto loan on my own. I checked with a few credit unions and banks, all of whom quoted rates around 5.9% to 6.4%.
Coincidently, or perhaps not coincidently, I received a letter from a company called Lease End. I had never heard of them and was about to toss it, but curiosity got the best of me. It explained that Lease End is an online service that finds you a loan by checking with a number of providers. Their website promises: “No haggling, no hidden fees, no DMV lines. We handle everything from payoff to titling — so you can sit back while we do the heavy lifting.”
Instead of contacting the lenders one by one, you provide Lease End with your lease details and personal information, and they find their best rate. If you agree, they handle the rest. The company says it processes roughly 3,000 lease buyouts per month and has completed over 67,000 since their launch. Naturally, I tend to be skeptical of claims that sound too good to be true, so I checked the reviews.
While several companies claim to offer similar services, none had the volume of positive feedback that Lease End had accumulated. The Better Business Bureau lists Lease End as an A+ accredited business with a customer rating of 4.63 out of 5 stars across over 200 reviews. On Trustpilot, they held a 4.8 out of 5 rating from more than 2,200 reviews, with 93% rated five stars.
I decided to call them and pursue cautiously. The representative, located at their Idaho headquarters, explained the process. He assured me they would shop around for the best rate based on my credit score and noted that they charge no fees to the customer—they are paid directly by the lending institutions. They did offer GAP insurance and an extended warranty, but when I declined, they didn’t push the issue further.
I spent a couple of days thinking it over before deciding to proceed with an application. This time, I spoke with another agent named Houston who spent about thirty minutes walking me through the paperwork. I wasn’t committing to a loan yet—just authorizing them to find their best rate. He explained they would contact Lexus Finance for the official buyout figure and begin shopping for rates. The submission did initiate a few hard credit inquiries that I was notified about from the credit bureaus. (Inquiries for the same car loan is counted as a single check.)
The next day, he called back: Capital One offered to fund the loan at 5.1% interest. I also learned the true payoff to Lexus was slightly lower than what the dealer had originally quoted, as the dealership had tacked on a lease termination fee.
I accepted the offer from Lease End and Capital One, and the process is now moving along quickly. Everything was completed online. Lease End is handling the paperwork, registration, and title transfer, coordinating directly with both Lexus and Capital One. They set up a personalized online dashboard showing my status and remaining steps.
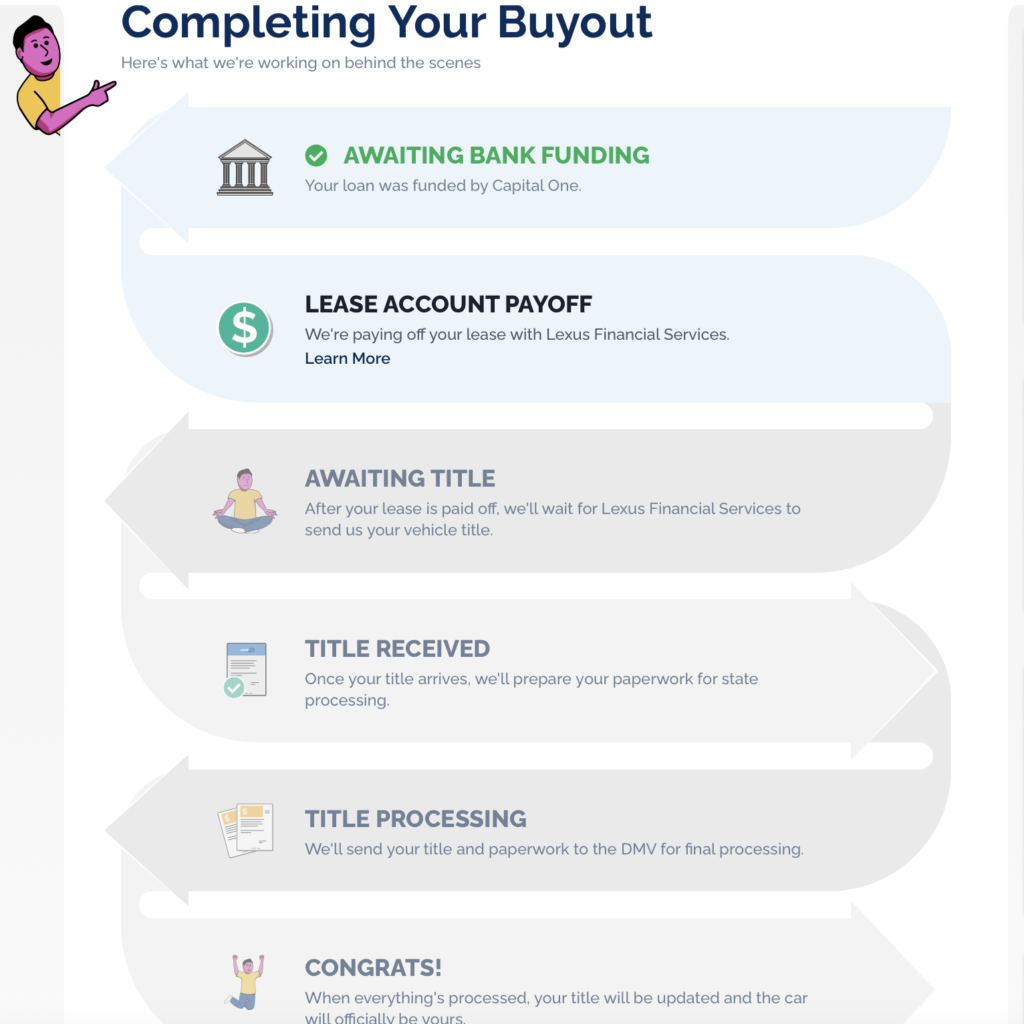
.
Based on my experience Lease End is well worth trying. It may not always get you the best rate, but it’s a lot more efficient than checking lending institutions on your own and, most importantly, avoids dealing with your dealer who seems to always have something to sell you that you have little need for.

I’ll start with the obvious correction:
“…avoids dealing with your dealer who seems to always have something to sell you that you DON’T NEED OR WANT [never knew you needed].”
I have nothing to say about Lease End specifically, but the whole idea of platforms that do nothing but promise to ease the burden of dealing with other platforms strikes me as end-stage ensh*tification,